Joint, separate or somewhere in between? How couples can organise bank accounts without confusing unity with financial dependence
Some couples combine every salary, savings account and household expense. Others keep their finances almost entirely separate. Many use a joint account for common costs while retaining individual accounts for personal use. None of these arrangements is automatically more loving or responsible. A joint account can simplify bills and make shared goals clearer. Separate accounts […] The post Joint, separate or somewhere in between? How couples can organise bank accounts without confusing unity with financial dependence appeared first on NewZimbabwe.com.
 Black News
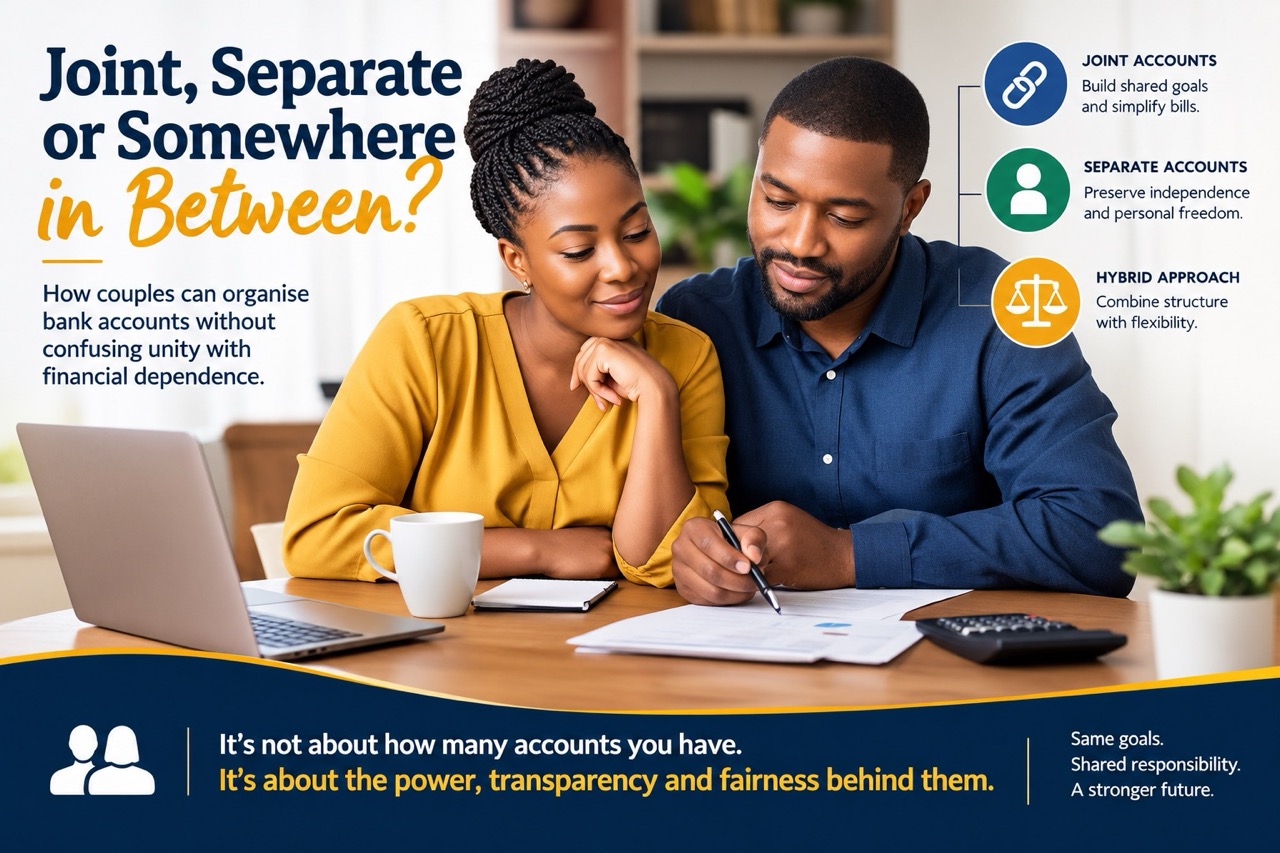
Some couples combine every salary, savings account and household expense. Others keep their finances almost entirely separate. Many use a joint account for common costs while retaining individual accounts for personal use.
None of these arrangements is automatically more loving or responsible. A joint account can simplify bills and make shared goals clearer. Separate accounts can preserve independence. A hybrid arrangement may offer both structure and personal freedom. The success of any system depends less on the number of accounts than on the power and responsibilities attached to them.
A joint account is a financial tool, not proof of trust.
Money can enter one account while control remains in one person’s hands. One spouse may manage the cards and transfers, and decide what counts as necessary spending. On paper, both have access. In practice, one person controls the household’s financial choices.
The opposite can also be true. A couple may keep separate accounts while remaining transparent about income, savings and shared plans. Each contributes towards agreed costs, both understand the household’s position and neither uses independence to avoid responsibility.
A marriage can have three accounts and one financial plan—or one account and two competing agendas.
The real question is whether both spouses have visibility, dignity and a voice. Can each meet ordinary needs without humiliation? Do both influence decisions about saving, borrowing and major purchases?
This matters where incomes differ. The higher earner may treat salary as evidence of greater authority. Yet one spouse may earn less because they care for children, manage the home, reduce working hours or support the other’s career. Those activities do not appear on a payslip, but they help create the conditions in which the higher income is earned.
A higher salary does not purchase a larger vote in the marriage.
A non-earning spouse may contribute no cash while carrying responsibilities that would otherwise require childcare, domestic help or career sacrifice. Treating household money as belonging mainly to the wage earner ignores the wider economics through which that income became possible.
No adult should have to request money for every ordinary expense as though receiving an allowance from a parent. Dividing financial tasks can be efficient, but the spouse who pays the bills should not become the only person who understands or controls the system.
In a fully joint arrangement, most income enters shared accounts. Bills, savings, investments and personal spending come from the same pool. This can make the household’s position easier to see, remove monthly calculations over who owes what and recognise that income supports a household created by both people.
Yet joint accounts do not automatically create equality. When every purchase is visible, transparency can become surveillance. The arrangement becomes more troubling when one person controls access or decides which expenses are legitimate. Couples should also understand the bank’s mandate, including what either holder can withdraw or arrange.
Joint money without joint decision-making is not financial partnership.
A workable joint system requires shared knowledge, not merely shared names. Both spouses should understand the household’s income, debts and savings. Each should also have personal spending money that can be used without explanation. Its purpose is not secrecy, but dignity.
At the opposite end, each spouse may receive income into an individual account, pay an agreed share of household costs and manage the remainder independently. This may suit couples who value autonomy or have established obligations.
However, separate accounts can create distance when they are not supported by a common plan. A couple may divide bills efficiently while never discussing savings, investments or retirement. One spouse may accumulate wealth while the other uses almost all their income to keep the household running.
Separate accounts can protect independence, but they should not create separate financial futures.
Contribution rules are central. An equal cash split may appear neutral but become unfair where incomes differ sharply. A proportional approach, in which each contributes according to income, may leave both with reasonable personal freedom. Other couples may pool income for shared commitments and transfer similar personal allowances to each spouse.
There is no single formula for every household. What matters is whether the arrangement reflects earning capacity, unpaid work and the choices made together. Separate accounts should not leave one spouse with most of the disposable income while the other carries the household.
Between fully joint and fully separate arrangements lies the hybrid model. Income may enter personal accounts before agreed transfers are made into a household account. Alternatively, salaries may enter a joint account, from which personal allowances move into individual accounts. Shared savings can also be separated from everyday spending.
Personal accounts can preserve freedom; joint accounts can organise responsibility. The two do not have to compete.
A practical version may include one account for bills, another for shared savings and one personal account for each spouse. But couples must still decide what counts as shared, how contributions are calculated and how additional income relates to common goals.
These questions matter especially in diaspora households supporting obligations across countries. One spouse may be paying rent or a mortgage where the couple lives, supporting relatives elsewhere and investing in property abroad. Without a common framework, each may treat personal commitments as untouchable while expecting the other’s income to carry the household.
Financial independence should give each spouse dignity, not give one spouse an escape from shared responsibilities.
Whatever structure a couple chooses, it should answer three questions: how common obligations will be funded, how shared wealth will be built and how each spouse will retain reasonable personal freedom.
It should also change when life changes. A system that works while both spouses are employed may become unfair during parental leave, illness, unemployment, study or caring responsibilities. A contribution formula agreed when both earned similar salaries may remain unchanged after one person’s earning capacity falls.
A financial arrangement can remain equal on paper long after it has become unfair in practice.
Couples should examine not only what each contributes, but what remains afterwards. One spouse should not finish every month with substantial savings and freedom while the other has almost nothing because they carried responsibilities that reduced their income.
A new child, promotion, relocation, job loss or business launch should trigger a review. The conversation need not inspect every purchase. It should ask whether shared costs, saving and personal freedom remain balanced.
The arrangement must also work when life becomes unpredictable. If only one person understands the accounts, insurance, debts and investments, the household may become financially paralysed during illness or bereavement.
Both spouses should know where income is held, which bills are paid, what debts exist, where important documents are kept and how essential money can be accessed. They do not need to memorise every password, but neither should be unable to continue the household’s financial life.
The spouse who manages the money should not become the spouse who owns the information.
Personal accounts may preserve independence, but the household should not be unable to pay for housing, food and utilities because all accessible funds are controlled by one person. Insurance, wills, pensions and beneficiary nominations also form part of the same system.
Account structure should follow the financial plan, not replace it. A couple may share bills without building shared wealth, or put every pound into one account without agreeing on priorities.
A marriage can have one bank account without having one financial direction.
For some couples, a fully joint arrangement will simplify financial life and express partnership. For others, separate accounts with agreed contributions will preserve autonomy while meeting common obligations. Many may find that a hybrid arrangement offers the best balance.
No structure removes the need for communication. Joint accounts can be controlled unfairly. Separate accounts can conceal widening inequality. Hybrid arrangements can become symbolic if the responsibilities beneath them are never discussed.
Two people do not need one bank account to build one future. They need a system in which responsibility is shared, information is visible and neither spouse’s independence depends on the other’s permission.
The best account structure is not the one that looks most united. It is the one that gives both spouses visibility, dignity and a fair voice.
Dr Shame Mugova is a Lecturer in Finance at Birmingham City University. The views expressed are his own and do not necessarily reflect those of NewZimbabwe.com
The post Joint, separate or somewhere in between? How couples can organise bank accounts without confusing unity with financial dependence appeared first on NewZimbabwe.com.