Measuring Africa’s Renewable Success: Operating Capacity Over Announcements
Africa’s energy transition is about more than expanding solar farms, wind projects and transmission networks. It also depends on whether the continent can manufacture, assemble, maintain and eventually recycle the.
 Black News
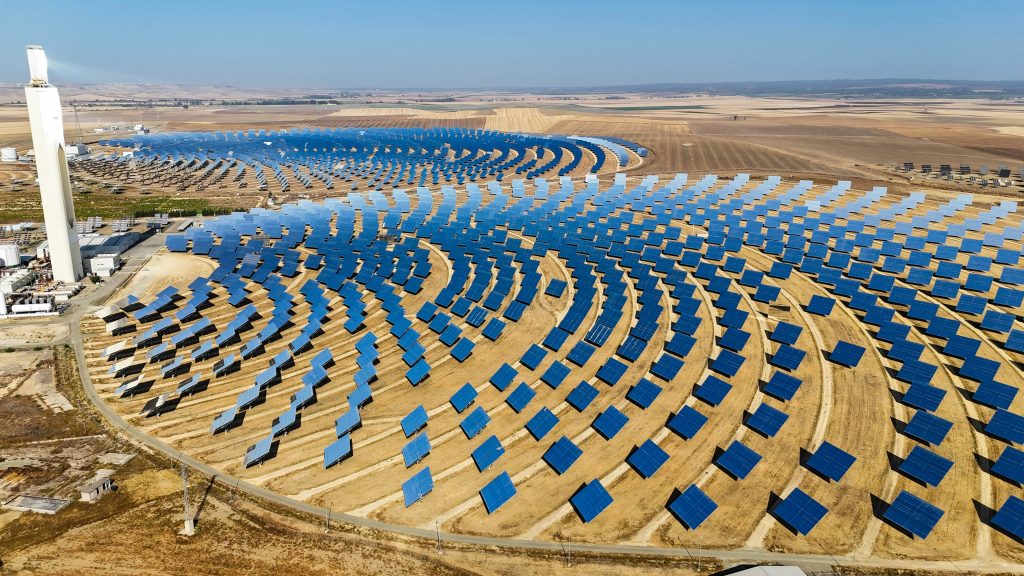
Africa’s energy transition is about more than expanding solar farms, wind projects and transmission networks. It also depends on whether the continent can manufacture, assemble, maintain and eventually recycle the technologies required to power these systems. Without stronger domestic industrial capacity, Africa risks expanding renewable energy deployment while remaining dependent on imported equipment and foreign supply chains.
The distinction between announced projects and operational production is therefore critical. Across the continent, several countries have made significant commitments to renewable energy manufacturing and green industrialisation. However, their progress varies considerably, and the distance between investment announcements and functioning industrial capacity remains substantial.
READ ALSO: Côte d’Ivoire’s 46MW Biomass Plant: Turning Agricultural Waste into Energy and Economic Value
Namibia’s green hydrogen ambitions illustrate the difference between project development and commercial operation. Hyphen Hydrogen Energy is developing a proposed project valued at more than US$10 billion, targeting annual production of approximately two million tonnes of green ammonia at full scale. In September 2026, the African Development Bank selected the project for a prospective US$5.93 million reimbursable grant to support development activities towards a Final Investment Decision (FID). The funding is for project preparation, not construction. Hyphen’s FID timeline has been pushed to the end of 2027, meaning the project remains in development rather than commercial operation.
Kenya offers a different example. Its renewable electricity generation, supported by geothermal, hydro and wind resources, provides a strong foundation for green industrialisation. Geothermal capacity stood at approximately 940–988 MW in recent official assessments, making Kenya Africa’s leading geothermal producer. However, renewable electricity generation should not be confused with renewable technology manufacturing. KenGen’s Olkaria Green Energy Park has attracted five investors across sectors including data centres, green fertiliser, electric mobility, steel fabrication and fish-feed production. These commitments demonstrate industrial interest, but they do not establish domestic solar panel manufacturing capacity.
The Democratic Republic of Congo (DRC) and Zambia are pursuing a regional battery value chain built around their mineral resources. Both countries have designated special economic zones in Musompo and Ndola to attract investment in battery production and related industries. Yet an October 2026 assessment by the International Institute for Sustainable Development found that important investment-readiness challenges remain. Inadequate and unreliable electricity, cross-border logistics constraints, regulatory uncertainty and skills shortages continue to affect the zones. The assessment also emphasised that neither country independently possesses all the minerals, industrial capabilities and market scale required to support a complete battery value chain.
Nigeria’s solar panel assembly sector is advancing, although from a relatively small base. The Rural Electrification Agency reported that domestic manufacturing capacity had increased from approximately 120 MW to 300 MW over two years. This growth reflects the expansion of existing producers and the entry of additional manufacturing lines. However, capacity figures should not be mistaken for actual annual production. Tranos broke ground on an 800 MW-per-year solar panel factory in Ogun State in June 2025, but Ember’s 2026 assessment reported that its first production line had not yet been commissioned. Nigeria’s proposed partnership with LONGi for a 500–1,000 MW manufacturing facility also remains an investment proposal rather than an operating factory.
The continental picture reinforces the scale of the challenge. Ember estimates that up to 94% of solar panels installed in Africa are still imported from China. Its analysis of Chinese trade data recorded 19 GW of solar cells and 9 GW of wafers exported to Africa over the 2.5 years to June 2026, compared with an estimated 2.7 GW of solar panels manufactured on the continent during the same period. Africa’s nominal solar panel manufacturing capacity is expected to reach approximately 3.5 GW in 2026, but factory capacity does not necessarily translate into equivalent production. Ember also cautions that some manufacturing facilities in Egypt and Tanzania are oriented towards export markets, particularly the United States, rather than African buyers.
Morocco demonstrates the scale of investment being pursued in battery manufacturing. In July 2026, the African Development Bank approved a €100 million loan for Gotion Power Morocco’s proposed integrated lithium iron phosphate battery gigafactory. The first phase is designed to produce 10 GWh of battery cells and packs annually, with a longer-term expansion target of 100 GWh. The project is expected to achieve a 70% local industrial integration rate. However, loan approval and project development should not be presented as evidence that the factory is already operational.
The measure of Africa’s renewable manufacturing progress must therefore extend beyond investment announcements and proposed production targets. For each project, the relevant questions are whether construction has been completed, production lines have been commissioned, output is being delivered, and meaningful stages of the value chain are performed locally. It is equally important to establish whether manufacturers can compete on cost, quality and reliability.
Africa’s renewable energy market is expanding, creating an opportunity to build domestic industries around the technologies driving that growth. But the continent will capture a greater share of the economic value only when announced capacity becomes functioning production, supported by reliable infrastructure, technical skills, competitive financing and regional markets. Until then, Africa’s energy transition will continue to depend heavily on technologies manufactured elsewhere.